

Current Rates
All rates are fixed and effective dates vary for each.
Regular Loan Program
- 6.375%, effective Sept. 29, 2026
Montana Board of housing Plus 0% Deferred Down payment assistance Loan Program
- 6.625% First mortgage interest rate, effective Sept. 29, 2026
- 0% Second mortgage interest rate; APR 0.30% based on $6,500 loan
Set-aside Loan Program
- 6.125%, effective Sept. 29, 2026
Montana Veterans Home Loan Program
- 5.375%, effective Sept. 29, 2026
Bond Advantage Down Payment Assistance Program
- 6.625% First mortgage interest rate, effective Sept. 29, 2026
- 6.625% Second mortgage interest rate, 15-year term, effective Sept. 29, 2026
80% Combined Program
- 6.625%, effective Sept. 29, 2026
COMMUNITY LAND TRUST
- 6.125%, effective Sept. 29, 2026
Habitat for Humanity
- 2%
Habitat for Humanity IN A Community land trust
- 5.875%, effective Sept. 29, 2026
Income and Purchase Price Limits
To be eligible for an MBOH loan, the purchase price and total annual household income cannot exceed the limits below. Exception for the Montana Veterans’ Home Loan Program* and MBOH Plus 0% Deferred Down Payment Assistance Program** are noted.
The limits listed below apply to the Regular Bond Program, Bond Advantage Program, 80% Combined Program and Mortgage Credit Certificate Program.
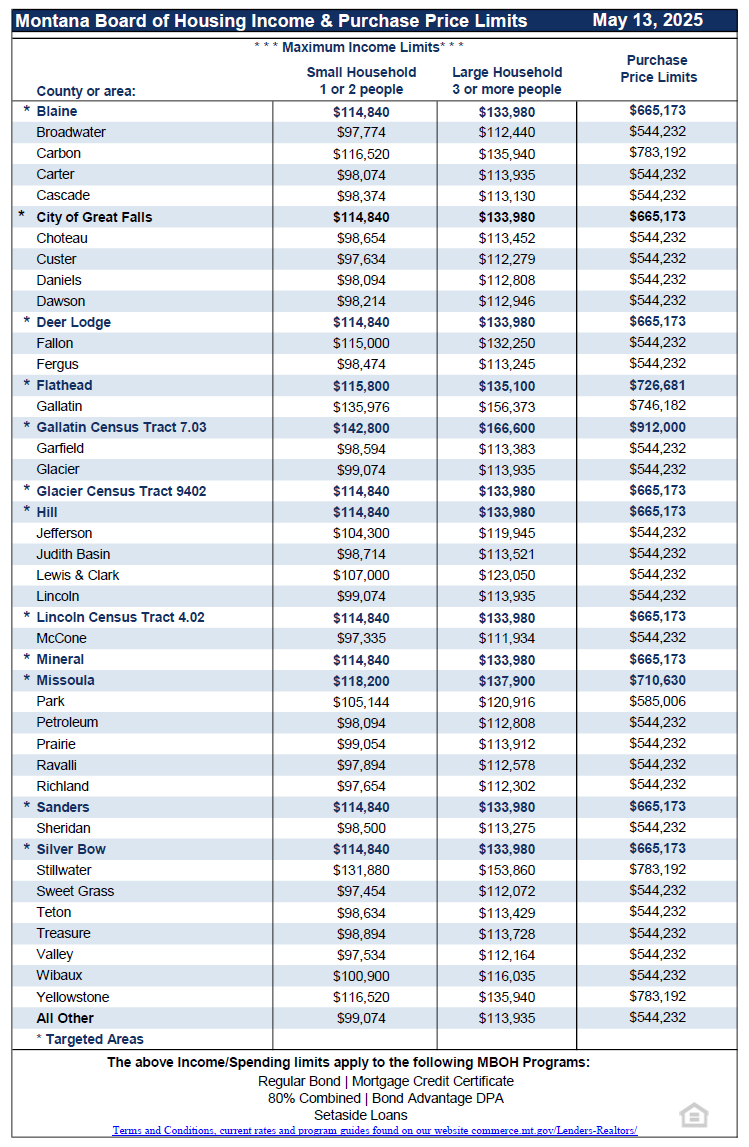
For those counties that are not listed, the MBOH uses the income and purchase price limits labeled “All Other Areas” set forth at the end of the list of counties. *The Montana Veterans’ Home Loan Program has a loan amount limit of $538,036, effective July 24, 2026. No income, purchase price or asset limits apply. Borrower must be a true first-time homebuyer and never owned their principal residence. Targeted areas do not apply to this program.
** The MBOH 0% Deferred Down Payment Assistance Program has an income limit of $80,000 for a household with one or two people, and $90,000 for a household of three or more people.
MBOH Income and Purchase Price Limits (PDF)
How to calculate income
MBOH must consider household income, which can be different than the qualifying income the lender uses for underwriting purposes. The guide below can be helpful in calculating household income.
Visit the Lender Webpage